
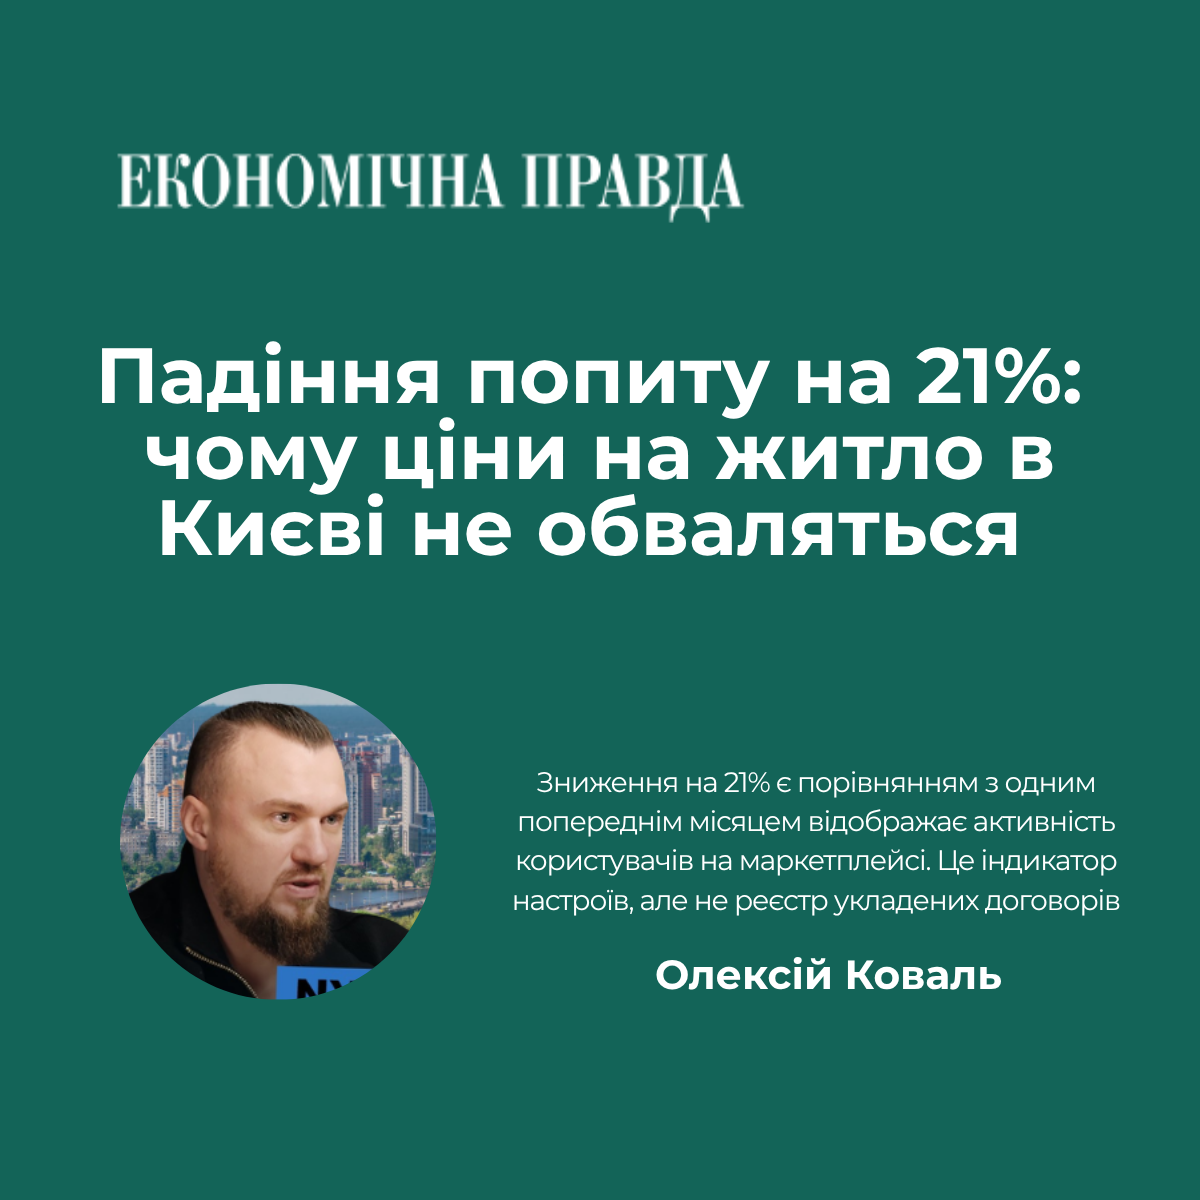
Analyzing the June data, Perfect Group CEO Oleksii Koval emphasizes that a statistical drop in interest should not be equated with a decline in real sales.
“The 21% decrease is a month-over-month comparison that reflects user activity on a marketplace. It is an indicator of sentiment, not a registry of finalized contracts.”
The expert notes that under current price dynamics, the primary market has a firm bottom line shaped by rising project implementation costs.
“On the primary market, this floor is increasingly defined by prime cost. In May 2026, construction and installation costs in the residential sector were 18.7% higher than a year earlier. Materials, energy, logistics, and financing are getting more expensive, while qualified construction workers remain in short supply. On top of that, there are added costs for autonomous power generation, shelters, and backup engineering systems.”
That is why current figures should be viewed not as a signal to expect a collapse, but as a period of temporary buyer advantage.
“Today’s market gives buyers something that barely existed in 2021: time to choose, negotiate, secure installment plans, and influence the final price. But this does not mean that nominal prices will see a widespread fall. That would require a combination of oversupply, cheaper construction, and a large number of forced sellers. None of these preconditions exist in Kyiv.”
Read more details in the full article.

 Want to calculate the cost of an apartment?